Midterm Elections: Our Economic Outlook Remains Intact
The Democratic Party won a majority in the House and Senate in Tuesday’s midterm elections, ending Republican congressional control. This outcome introduces a modest shift in the policy outlook but is unlikely to materially disrupt the broader drivers of economic growth. With Democrats gaining control of Congress, fiscal priorities are likely to shift toward healthcare and other nondefense spending, although the president’s veto power and legislative constraints are likely to limit the potential for sweeping policy changes. Neither party appears focused on meaningful deficit reduction, suggesting that elevated fiscal deficits are expected to remain a feature of the economic backdrop. While fiscal policy provided a boost to growth in 2026, that impulse is expected to moderate next year, with any additional spending under a Democratic Congress unlikely to meaningfully affect either the deficit outlook or economic growth.
One of the more consequential implications of the election is the potential for increased regulation of data center development, which may have contributed to volatility in technology stocks following the results. State and local opposition has become more prominent, with concerns surrounding electricity costs, environmental impacts, and tax incentives driving proposals for additional restrictions and moratoriums, including in Texas and New York. In the 2026 election, seven states with planned data center capacity elected governors who publicly back moratoriums (see Exhibit 1, states highlighted in red). These states account for about half of planned capacity. Going forward, additional regulation could delay projects and increase costs in an industry already facing infrastructure bottlenecks and rising construction expenses.
Exhibit 1: Operating vs. Planned Data Center Capacity by State
Key takeaway: State-level data center moratoriums could affect half of planned capacity.
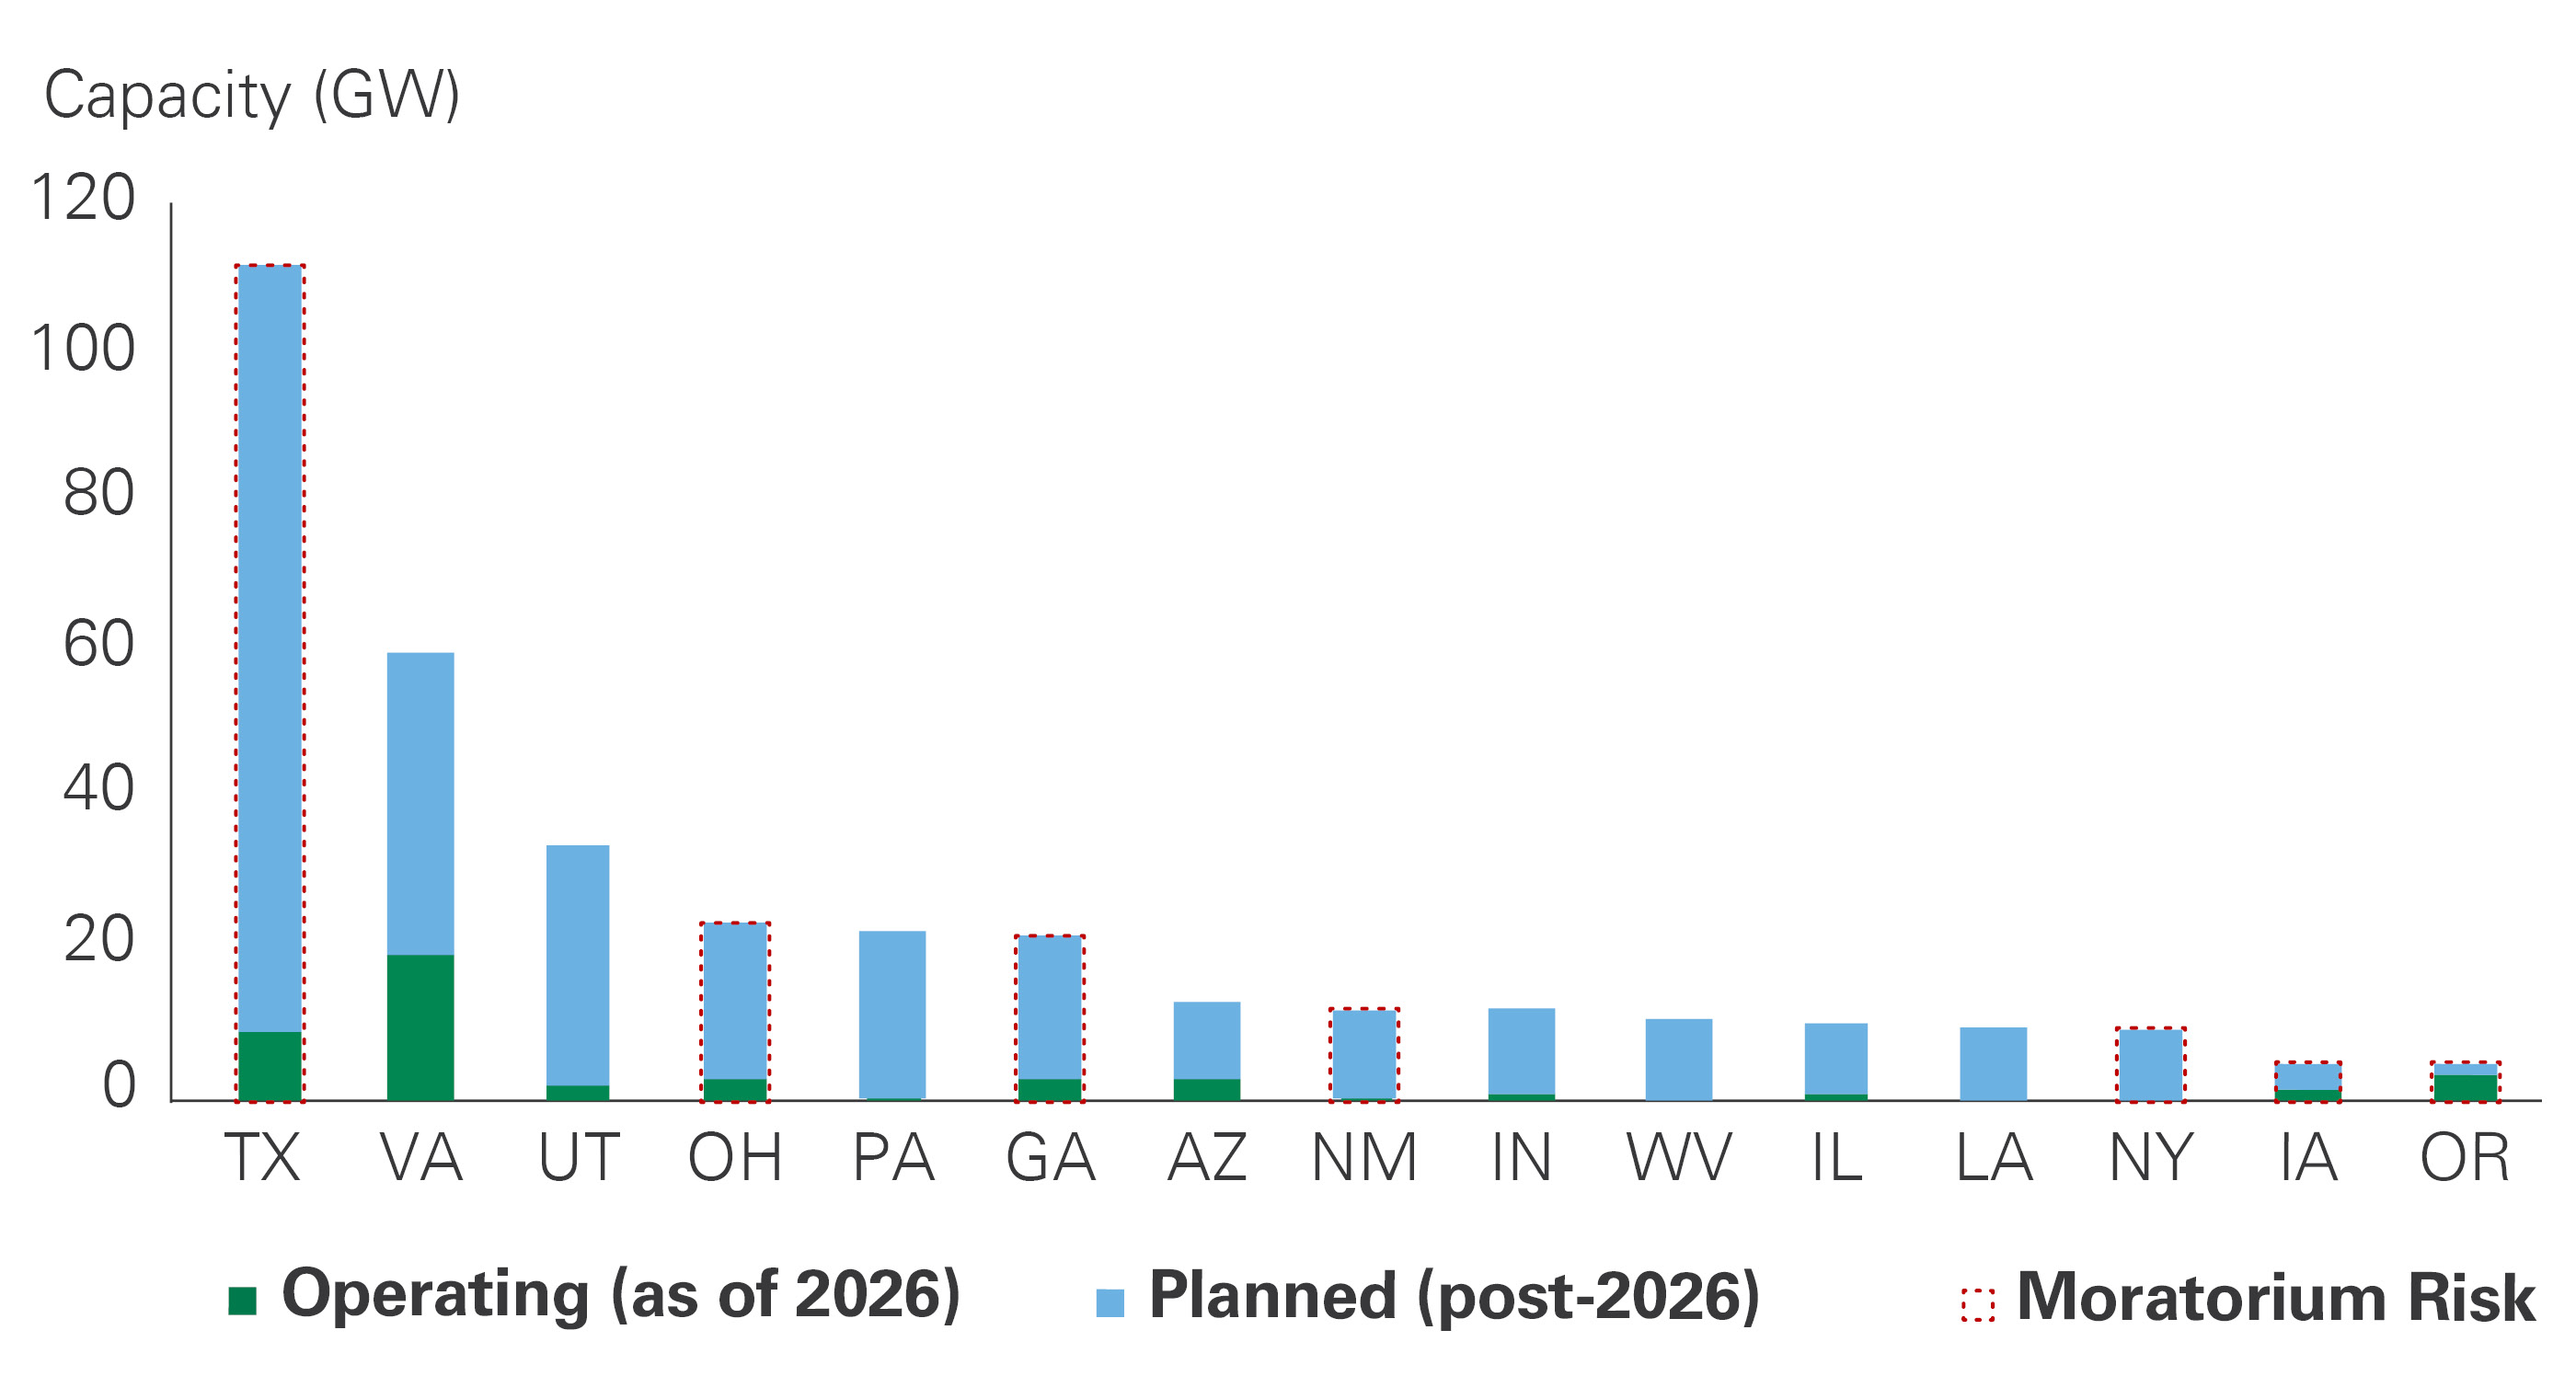
Stacked bar chart comparing operating capacity as of 2026 with planned capacity after 2026 across 15 states, measured in gigawatts (GW). Green represents operating capacity, and blue represents planned capacity. Texas has the largest combined capacity at approximately 112 GW, followed by Virginia at 60 GW and Utah at 34 GW. Ohio, Pennsylvania, and Georgia each have approximately 22–24 GW. Arizona, New Mexico, Indiana, West Virginia, Illinois, Louisiana, and New York each have approximately 10–13 GW, while Iowa and Oregon each have about 5 GW.
Planned capacity accounts for most of the total in nearly all states. Virginia has the largest operating capacity at approximately 19 GW, followed by Texas at 9 GW. Red dotted outlines flag moratorium risk in seven states: Texas, Ohio, Georgia, New Mexico, New York, Iowa, and Oregon.
All told, forecasts for data center capacity have not changed meaningfully following the election outcome as data center regulation has become increasingly bipartisan and projections have already incorporated these headwinds, in our view. Furthermore, moratoriums are not necessarily permanent bans but may be lifted once additional regulatory reviews are completed or protections for local communities are established. Many of the proposed policies focus on greater transparency, cost-sharing, local incentives, and oversight rather than on prohibiting new development altogether. Additionally, the decentralized nature of state-level regulation provides developers with the flexibility to redirect investment toward jurisdictions with more favorable regulatory environments. For example, developers are already shifting new projects to Louisiana, Oklahoma, North Dakota, and Wyoming — states with low-cost natural gas and opportunities to build their own power plants. We will monitor federal legislation, though passage looks unlikely given President Trump’s support for data center development and his veto power. Bipartisan permitting reform, which could accelerate approvals for power lines and plants, remains on the agenda.
Despite these growing regulatory headwinds, we do not expect the midterm results to significantly derail the broader AI capital spending (capex) cycle. Demand for computing capacity continues to outpace supply, supporting substantial investment commitments from large technology companies with diversified revenue streams and strong balance sheets. From an economy-wide growth perspective, the majority of AI-related capex is directed toward computers, servers, and semiconductors, rather than the physical construction of data centers, though they are inherently linked (see Exhibit 2). In the near term, equipment spending can continue through projects already under construction and upgrades to existing facilities, helping to mitigate the impact of regulatory delays on the broader investment cycle. As a result, restrictions on new construction may have a more pronounced impact on local economic activity and construction employment than on aggregate capital spending.
Ultimately, a sustained slowdown in the investment cycle would more likely stem from deteriorating credit conditions, higher interest rates, or weakening demand than from regulation alone. With the four largest hyperscalers accounting for 75% of capex growth, however, funding is less vulnerable to these pressures, and these companies are less likely to alter their investment plans in response to higher interest rates or regulatory costs. If anything, hyperscalers are better positioned than companies such as neoclouds in an environment with greater regulation and higher interest rates. A shallower pace of capacity expansion could also allow more time for monetization to catch up with spending.
Exhibit 2: Contributions to GDP Growth from AI Capex
Key takeaway: The AI investment cycle remains a strong tailwind for economic growth.
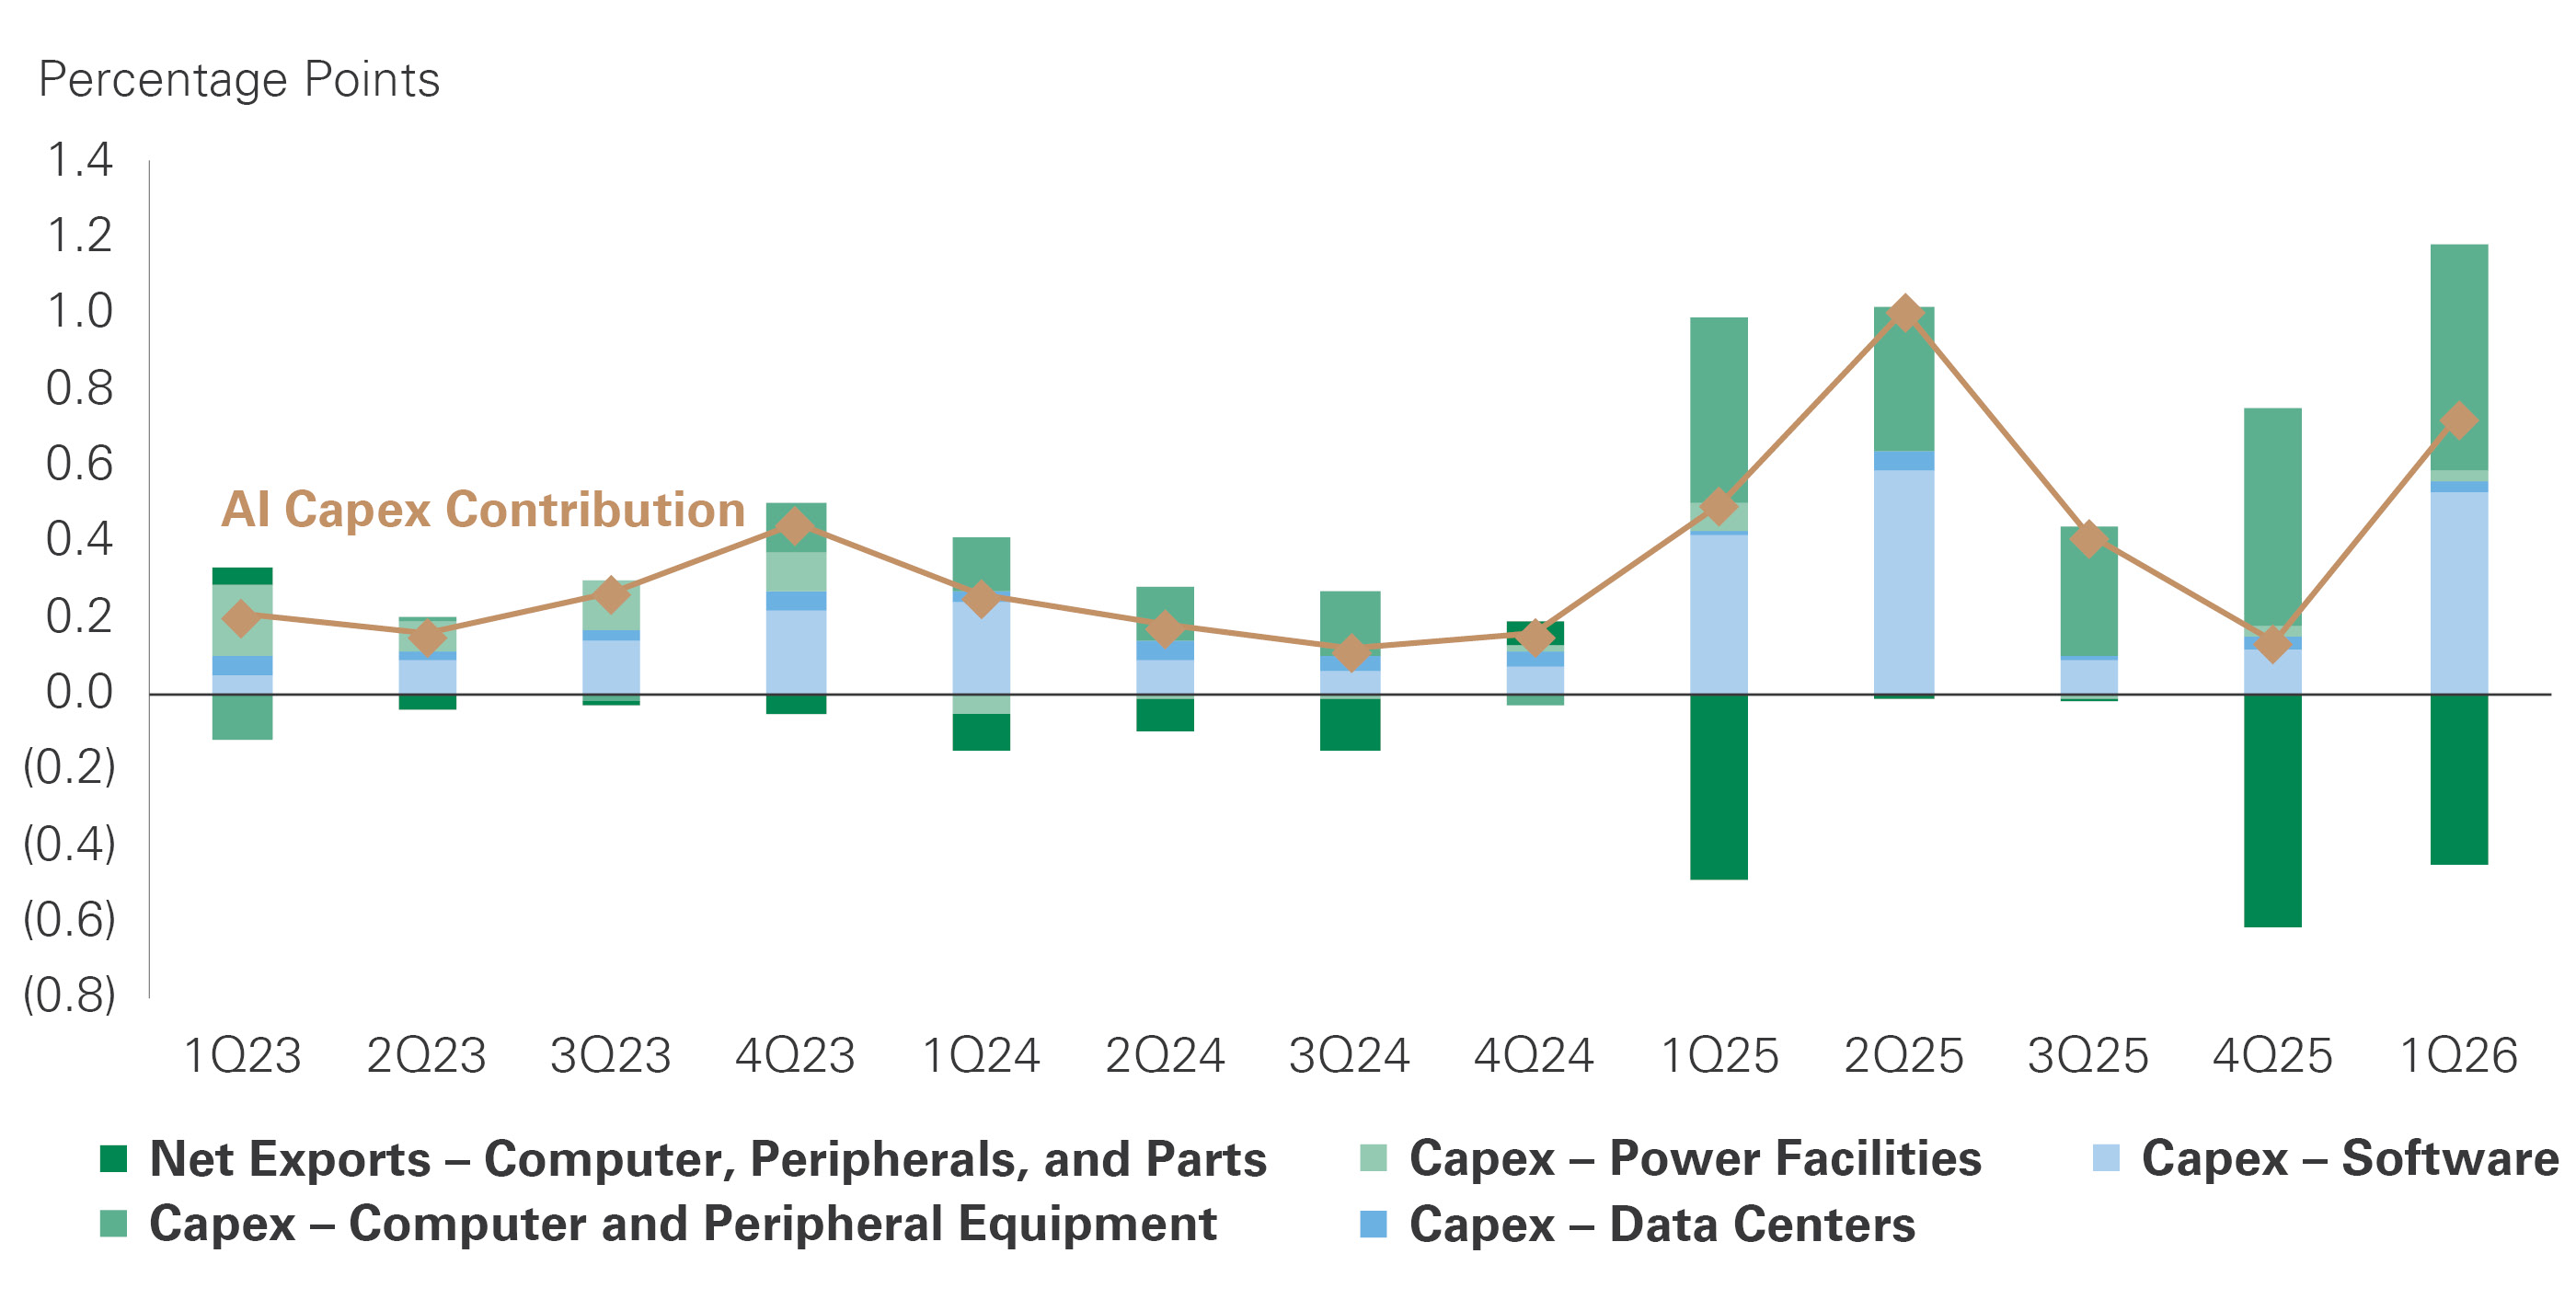
Combined stacked bar and line chart showing the AI capital expenditure contribution, measured in percentage points, from the first quarter of 2023 through the first quarter of 2026. The stacked bars show contributions from capital expenditures on software, data centers, power facilities, and computer and peripheral equipment, along with net exports of computers, peripherals, and parts. A tan line with diamond markers shows the combined contribution.
The combined contribution remains positive throughout, ranging from approximately 0.1 to 0.45 percentage points during 2023 and 2024. It rises to about 0.5 percentage point in the first quarter of 2025 and peaks at 1.0 in the second quarter. It then declines to 0.4 in the third quarter and approximately 0.1 in the fourth quarter before rebounding to 0.7 in the first quarter of 2026.
Software and computer equipment spending provide the largest positive contributions in the strongest recent quarters. Negative net export contributions offset some of this spending, particularly in the first and fourth quarters of 2025 and the first quarter of 2026. The largest negative net export contribution is approximately 0.6 percentage point in the fourth quarter of 2025.
Source: The Federal Reserve
We believe that the broader economic environment remains favorable. Nominal economic growth has shifted to a higher range relative to the pre-pandemic period, reflecting both resilient real activity and a higher inflation backdrop. The ongoing capex cycle, which is unlikely to be materially disrupted by higher regulatory costs, has become an increasingly important contributor to growth, with the potential for productivity improvements to support economic activity over a longer horizon, not just the near term. At the same time, stronger capex-led growth and persistently elevated fiscal deficits are likely to sustain upward pressure on longer-term Treasury yields. While an abrupt slowdown in AI investment would present a headwind to growth, the associated decline in bond yields could provide some offsetting support to more interest-rate-sensitive areas of the economy.
Overall, the midterm elections may alter the composition of government spending and introduce additional regulatory obstacles for data center development, but they do not fundamentally change our constructive outlook for economic growth. We continue to view the AI capital spending cycle and structurally elevated fiscal deficits as two important forces shaping the economic and interest-rate environment. The sustainability of AI investment, rather than the election outcome itself, is likely to be the more consequential determinant of the growth outlook over the coming years.
Going forward, we believe regulatory headwinds and higher interest rates leave higher-quality companies, with strong balance sheets and the flexibility to navigate the shifting backdrop, in a relatively more favorable position. We will continue to assess the implications of evolving data center regulations for our portfolio holdings, recognizing the risks to development timelines and capital costs while maintaining a constructive view of the long-term investment opportunity.
Past performance is no guarantee of future results. This material is provided for your general information. It does not take into account the particular investment objectives, financial situations, or needs of individual clients. This material has been prepared based on information that Bessemer Trust believes to be reliable, but Bessemer makes no representation or warranty with respect to the accuracy or completeness of such information. This material contains forward-looking statements, including views on economic conditions, fiscal and regulatory developments, and industry trends. Forward-looking statements are based on current expectations and assumptions that we believe to be reasonable, but they are inherently uncertain and are not guarantees of future events or results. Actual outcomes may differ materially from those expressed or implied due to a variety of factors, including changes in economic conditions, government policy, legislation, regulation, interest rates, inflation, and market conditions. We undertake no obligation to update any forward-looking statement. Views expressed herein are current only as of the date indicated and are subject to change without notice. Forecasts may not be realized due to a variety of factors, including changes in economic growth, corporate profitability, geopolitical conditions, and inflation. The mention of a particular security is not intended to represent a stock-specific or other investment recommendation, and our view of these holdings may change at any time based on stock price movements, new research conclusions, or changes in risk preference.